Posts tagged "commoditization"

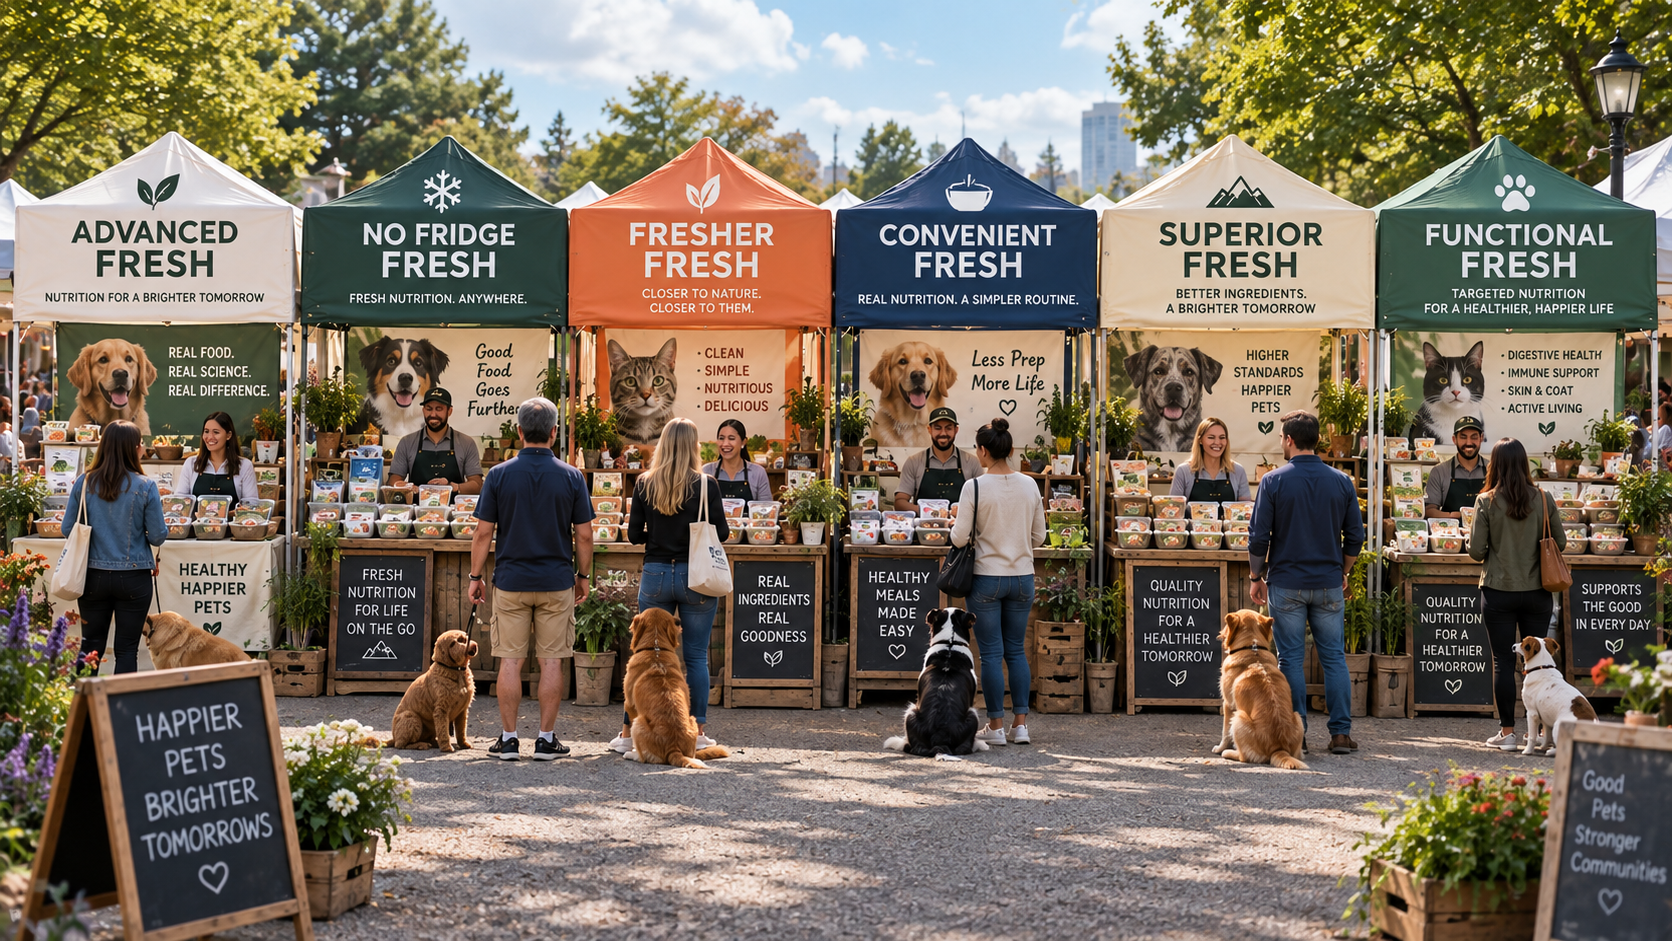
Pet food brands chasing each other into similar nutrition categories

What Happens When All Premium Pet Brands Fight Over the Same Territory?

September 23rd, 2026 Posted by Brand differentiation, brand marketing, brand messaging, Commoditization, Validation, Value proposition 0 comments on “What Happens When All Premium Pet Brands Fight Over the Same Territory?”

Innovation leverage is fading fast…

We are entering a period of uncertainty in the pet industry as underlying strategic challenges and product proliferation – accelerated by the extraordinary impact of AI – are reframing what competitive advantage looks like. Here we will pull apart and examine the forces at work, identify the impacts and launch a conversation about the next threshold of durable marketplace strength. Stay tuned for our recommendations at the end.

Premium pet brands have spent more than a decade expanding by segmenting the market into ever more specialized dietary propositions: grain-free, ancestral/biologically appropriate, raw, fresh, gently cooked, human-grade, limited ingredient, high protein, functional benefits, sustainably sourced, breed/life-stage solutions, probiotics, freeze-dried, etc. 

However, these successful innovations also escalated the competition. The competitors then normalized them, and what began as a meaningful brand distinction increasingly became a category expectation. 

Don’t get me wrong, product innovation is and will remain essential. However expecting product innovation to fuel lasting brand competitive leverage is becoming increasingly unrealistic.

In sum, here’s the strategic challenge we will examine:

  1. When nearly every premium pet food is nutritionally sound and on point, where should competitive advantage spring from?
  2. When the supply of premium pet food solutions outstrips demand and the law of economics flip, what should brands do to build and hold incremental gains?

Simply put, more brands and more SKUs and more innovation alongside enhanced nutritional claims are competing for a finite number of households, pet stomachs, shelf space and dollars. At some point, yet another product improvement stops creating proportional incremental demand. Instead it mostly redistributes existing demand. Slowing pet category growth makes this an imperative issue to confront now.

To its credit, the industry has invested enormous resources to improve what’s in the bag, can or pouch. And it worked. The nutritional quality available to pet parents is extraordinary compared with 15–20 years ago.

But there’s an unintended consequence:

  • The industry’s relentless pursuit of product superiority has produced an increasingly superior and rather closely aligned field of competitors who chase each other into every innovation territory.

Here’s the current essential truth…

High protein isn’t distinctive. Functional nutrition isn’t distinctive. Probiotics aren’t distinctive. Minimally processed isn’t unique. Human-grade isn’t nearly as distinctive as it once was. Freeze-dried isn’t. Fresh is already spreading among brands. Even claims around ingredient quality, veterinary expertise, and science-backed are increasingly shared territory.

Claim proliferation is upon us. According to Innova Insights 2025 launch data, among new products carrying a high-protein benefit, 71% also carried another health claim, 64% had a digestive-health claim and nearly half added a skin-health claim. Gut-health positioning appeared on 31% of global new launches; immune and skin health each appeared on 22%.

Fresh category is the latest expansion arena: 

Fresh began by successfully challenging assumptions about what pet food should be. Today fresh/frozen territory includes Freshpet, Farmer’s Dog, Ollie, JustFoodForDogs, Nom Nom and numerous others, while conventional premium manufacturers increasingly offer adjacent, similar formats. Fresh/frozen dog food posted a 24.5% CAGR from 2021–2025 versus 5.7% for the overall dog-food-and-treat category. What was once a category disruption transforms into another highly competitive segment.

The same process occurred earlier with grain-free and high-protein formulations. A claim can be true, important and compelling to consumers—and still have almost no competitive currency if a dozen brands are credibly making the same claim.

“High protein” is valuable but not differentiating.
“Science-backed” is reassuring but without being proprietary.
“Premium ingredients” is meaningful without offering separation.
“Veterinarian developed” forges trust but not ownership.

Pricing aside, what happens when brands prioritize reasons to believe over the more elusive yet critical trusted reasons to choose.

We should note, premium pet category strength continues to be a business driver. APPA reported 41% of dog owners and 38% of cat owners purchased premium food in 2024, both up from 2023.

Packaged Facts similarly found that 70% of dog and cat owners remain willing to pay more for foods offering health-and-wellness benefits. While the demand for premium benefits remains strong, what’s becoming harder is capturing a disproportionate share of that demand when so many brands make comparable benefit claims.

Let’s dive in on the underlying economic mechanism fueling current conditions

  • Innovation → success → imitation → proliferation → normalization → declining differentiation creates a condition where greater marketing investment is required to deliver the same year-to-year growth report card.

When competitors quickly replicate any innovation, the category may expand but without creating durable, sustainable advantage for the innovator.

The strategic competitive question then changes from:

“What can we make that is better?”

to:

“What can we become or offer that competitors cannot easily replicate?”

Where does the next increment of value surface from when most of the new nutritional niches have already been occupied?

Alongside innovation parity, an unseen contributor is helping enable these current challenges.

Ten years ago when premiumization was gaining momentum, the demand for higher quality ingredients, sourcing, manufacturing exceeded the supply. If you went to market with an authentically better product and handled the retail distribution, support and marketing requirements with skill and creativity, you likely saw solid growth and returns.

The red hot premium pet food market attracted more competitors in the same space, so brands began to look for unique needs, gaps and marketplace niches to serve while securing separation. This also worked for a time until most of those nutritional need gaps had been satisfied. 

Meanwhile many traditional barriers to entry in the pet food business have fallen.

Nutrition and science based formulators are readily available to help bring a product vision to life, while co-packers with sourcing expertise can serve as the asset light path to making a product. AI helps quickly build the business and operations plan while direct to consumer models make it considerably easier to get in front of potential customers (Packaged Facts states 39% of U.S. pet-food sales now occur online). The result is more and more new brands entering an already crowded marketplace seeking attention and share of wallet. One trip around the convention hall at SuperZoo helps verify the environment.

  • When supply starts to outstrip demand, the forces of competition begin to shift. Competition turns inward. Brands rush to participate in every corner of novel innovation and you begin to see brand similarity and sameness converge.

This impacts the strategic game plan when category conventions and normalized behaviors keep everyone locked into a cycle that replicates the same go-to-market moves. It simply gets harder and harder to squeeze incremental balance sheet gains year to year when the differentiation of choices narrows. Of note, pricing power also softens when brand distinction is diminished and becomes more trivial.

Prevailing business conditions are demanding improved strategic solutions

Consider the overall industry growth status reported by Packaged Facts: U.S. pet food and treat retail sales is projected to grow just 2.1% in 2026, to $70.45 billion, with a forecasted 3.2% CAGR from 2025–2030. The trend lines show a slower pace with dog and cat food sales rising 14% in 2020, 15% in 2021 and 2022, and 13% in 2023, before decelerating to 3.7% in 2024 and an estimated 2.8% in 2025. 

The supply of premium solutions continues to expand while category growth is moderating. This will simply intensify the fight for new, novel growth solutions. Now is the time to get on this.

So what’s next?

Places where the strategic pet brand building conversation can go:

Proprietary brand meaning—ideas, beliefs, cultural territory, communities and emotional propositions that aren’t bottled up in the formulation. This is a search for a ‘secret sauce’ or true north that may exist inside the organizations’ business structure, operations, behaviors, history, standards and beliefs.

Category creation—not another variant within an existing segment, but identifying an unmet pet nutrition problem that changes how stakeholders will think or behave. When most needs are already met, this is a tougher (but not insurmountable) question overall. 

Authority—owning trust, credibility and belief rather than merely making claims and assertions of performance and outcome. 

Business-model differentiation: experiences, services, retail models, personalization, relationships and other assets that competitors can’t duplicate simply by sending another formula to R&D.

In sum, the product still has to be excellent. Innovation remains essential. But durable advantage will increasingly come from proprietary meaning, authority, community, experience, business model, cultural relevance, category creation or some other asset competitors can’t duplicate by formulating an enhanced recipe and putting another package on the shelf.

An aligned avenue of strategic exploration: industry weaknesses and gaps

When there’s less leverage in products, the challenge to leadership teams is how to create added business value that isn’t easily over-run by competitors. Perhaps it’s time to solve systemic problems the industry faces that other brands elect to ignore or soft pedal.

If you zoom out to 30,000 feet and look at the pet food business there are numerous issues and weaknesses that your brand may be in a position to help solve, and in doing so, to step outside the conventional competition handbook to create a unique story your brand can champion.

A few examples –

  • Sustainability is an enormous hole the industry has talked around the edges of but no one leads at the strategic level to authentically resolve the supply chain (system 3) impacts.
  • While AAFCO standards enforce conformity on nutrition specifications monitored by state and federal regulators, still quality varies without verifiable consumer assurance of exactly what they’re getting. Is transparency really transparent?
  • The conventions of pet retail and product form hold the industry in a commodity-like grip cycle of bags, cans and pouches that present the product in the same fashion brand to brand. At times category conventions beg for fresh thinking.

These are not simple challenges, but one thing is for certain: there is a requirement now for real strategic work to investigate, interrogate and determine what the next roadmap to brand growth will look like. Here are some of the elements worthy of deep dive analysis:

What does the brand currently own?

Which claimed advantages are proprietary versus replicable?

Where has category convergence eroded differentiation?

Which latent brand assets have greater strategic potential?

What consumer/category white space could the brand credibly occupy?

What organizing proposition could drive innovation, communications, retail and go-to-market?

The next growth recipe may not be another recipe at all.

We should begin by answering a harder question: What can your brand credibly own that competitors cannot readily appropriate?

For premium pet brands fighting over increasingly similar nutritional territory, finding the answer may become one of the most consequential growth assignments ahead.

Looking for more food for thought? Subscribe to the Emerging Trends Report.

Bob Wheatley is the CEO of Chicago-based Emergent. Traditional brand marketing often sidesteps more human qualities that can help consumers form an emotional bond. Yet brands yearn for authentic engagement, trust and a lasting relationship with their customers. For more information, contact Bob@Emergent-Comm.com and follow on Twitter @BobWheatley.

Hoe to build an Iconic Brand

The Path to Enduring, Iconic Brand Strength

December 19th, 2025 Posted by brand advocacy, Brand Beliefs, Brand differentiation, CMO, Commoditization, Differentiation, Iconic Brands, Uncategorized 0 comments on “The Path to Enduring, Iconic Brand Strength”

Far too many brands miss the reason and the recipe

Two alarm bell-ringing stats about the current state of brand building:

  • According to a study from HAVAS – for roughly 78% of all brands, if they disappeared from the earth tomorrow, consumers wouldn’t really care and instead simply move on to another alternative. (Ahem).
  • Meanwhile 85% of advertising has zero impact on brand health.

What does this tell you about the state of brand strength, equity and the tools employed to achieve it? Have we so myopically moved to embrace transactional behaviors that the organization’s most important and valued asset is inadvertently being starved of the fresh thinking and investment it so justly deserves?

As an Emerging Trends Report reader, you likely agree that a strong brand is vital to sustainable, profitable business growth. We know healthy brands deliver lasting competitive advantage as evidenced through unflinching brand evangelism, rapid uptake of new product innovations and reliable repeat purchase. Even through economic down cycles — because the brand matters to users by virtue of its integral relationship with the consumers’ lifestyle priorities and beliefs system. By definition, this is the polar opposite of a commoditized business where price and deal frequency are the most meaningful separators.

Accelerating AI conditions are forcing rapid change

The AI tech revolution is currently conspiring against organic brand strength. It is our singular calling here to fight these growing odds that conflate uniqueness, suppress acts of courage and marginalize the competitive playing field.

What’s going on here?

Every successful brand will labor to own a prominent place in the consumers’ collective memory, such that it is more likely to be top-of-mind in buying decisions, while earning a higher probability of credible recommendation and exerting greater pricing power.

This bulwark of resilience and strength requires that brands be simultaneously different and relevant. The challenge now is the significant shift in why and how people attribute “difference and relevance” to brands that matter to them.

Different: is amazingly less about how a brand performs or how it is made — and more about the perception of why it exists, what it believes and how it expresses itself. Understood purpose and mission loom large.

Relevance: is now primarily attributed to how well a brand is aligned with the consumer’s social values and cultural viewpoint. Fulfilling a functional need remains important, but it’s not the dominant factor.

While brand minders may be aware of these shifts, many are drawing the wrong conclusions – resulting in a marketing approach that’s inadequate for one of two diametrically opposed reasons.

The myth of “Mirror Brands”

The meteoric rise of social media fed by proponents who recite its tactical virtues, has stoked a marketing religion focused almost entirely on winning people’s attention — at the expense of earning the right to be part of their lives. We characterize this marketing behavior as Mirror Branding – meaning the brand operates as a reflection of whatever’s currently hot in popular culture. This is blatant pursuit of virality for its own sake, grasps at fads while routinely mistaking memes for lasting memories.

An example of au courant tactic-over-strategy can be observed in a well-known popular deodorant brand that created a new product tied to a cryptocurrency – in itself inspired by a meme featuring a dog – and launched a campaign on a day when that cryptocurrency is in celebration mode.

Through forcing an impression of difference, occasionally a Mirror Brand can briefly secure a spotlight in popular culture. However, without the hard work of building deep-seated, enduring relevance, they operate on a shorter fuse that eventually fizzles and goes dark. An example in the UK, Liquid Death, the brand built on irreverent disruptive marketing memes, has withdrawn from the UK market after less than two years.

The fallacy of “Shadow Brands”

The marketing misstep that focuses blindly on visibility while failing to deliver any tangible emotional or cultural connection – this is the purview of Shadow Brands. Consumers are aware of their shadowy presence, but remain unclear about their beliefs, deeper substance and mission.

Shadow Brands aren’t necessarily irrelevant, but they can also fade away under pressure. Without a meaningful difference, it’s harder to maintain traction in hyper-competitive markets. Hate to say it, but this is a large and growing group and includes many distressed legacy brands, and a significant percentage of DTC brands that start to struggle after a promising start.

We must raise our ambitions on investing in brand strength and deeper meaning

To be more than a Mirror or Shadow, brands must construct enduring memories around the things people love and love to share. This is much easier said than done and requires full commitment to:

  • Conveying a point-of-view that is both meaningful and distinctive.
  • Adding value to consumers’ lives – supported through every expression and every experience.
  • Showing up in imaginative, inspiring ways that help define current culture.

Specifically, we should be focused on building “Iconic Brands”

Icons are never created in a heartbeat. It takes continuous commitment and investment over time. For example, the Dove brand’s “Campaign for Real Beauty” that celebrates self-esteem among women has been an evolving work-in-progress since 2004.

There is, however, an accelerant. Emergent has been a long-time proponent of integrated communications – the lashing together of multiple channels and disciplines to create a more effective and powerful brand. While the core principles of integration remain important, it’s simply not enough anymore. Radical changes to the marketing and business landscape mean both thinking and practice should evolve. This necessary leap forward is Interrelated Marketing.

It’s no longer possible to earn and maintain growth and business expansion through one-way communication alone. Ambassadors, evangelists and advocates must be enlisted as agents to act on the brands’ behalf. This will require mastering an intricate interplay between consumer-centered earned, owned, and paid media to create a flywheel that propels a brand towards Icon status.

Interrelated Marketing is designed to deliver this outcome by uniquely blending the four key drivers of modern brand success:

  1. Unlocking cultural relevance through compelling narratives at the intersection of a cultural tension and truth about the brand that shapes the conversation AND resonates with key audiences.
  2. Earning a solid enduring reputation by capitalizing on the influence of brand fans, respected expert voices and relevant credible institutions in authentic ways that cultivate positive, lasting renown.
  3. Designing reciprocal relationships through personalized experiences and value exchanges that customers will share with the brand.
  4. Driving desired response by satisfying an identified consumer preference with an effective, believable solution and call to action.

Many brands treat these four R’s — Relevance, Reputation, Relationship and Response — independently. But the magic happens when they are harnessed to a common purpose. That is the end-product of Interrelated Marketing: a connected ecosystem of expressions and experiences, where every piece of content, every social post, every event and every initiative builds seamlessly on the last.

The incredible impact of Icons

A reminder: marketing’s primary purpose is to build brands with the strength to deliver lasting competitive and economic advantage.

Despite what some pundits would have you believe, this requires setting the bar higher than simply mirroring an audience’s social media feeds or buying eyeball attention. Instead, the goal must be to earn a prominent, persistent place in a person’s memory by having a positive, enduring, meaningful impact on their lives. This is how brands achieve iconic status.

It’s a prize worth fighting for. Icons deliver impact via increased penetration; deeper, stickier customer relationships; stronger competitive defenses; and more powerful, resilient marketplace momentum. Finally, the bottom-line is the bottom-line: financial returns that are exponentially greater than the costs of its creation and delivery.

For businesses who are ready to make this commitment, Interrelated Marketing provides the right strategic drivers: every idea, every action, every behavior should demonstrate an obsessive focus on unlocking cultural relevance, deeper meaning, mission, belief systems and earning reputation that attracts strong 1:1 relationships.

Brands that succeed in conjoining these four drivers, with the right kind of creative thinking, will generate an impact that is unreasonably greater than the sum of the parts and eventually will win not just a larger share of the market but a greater share of the future.

The sea-change urgently pushing this agenda to the forefront of your planning

  • “The transformative potential of AI is not short-form video or treating it as a glorified search engine. It’s to advance human intelligence and what we’re capable of as a species.”

AI is upending how consumers discover brands, and large language models could soon be the window to a company’s reputation — as cast from its own point of view.

LLMs — the smart interloper in between brands and customers

The arrival of Agentic Advisors is at once favorable to guiding consumer decisions and more confident purchase outcomes by delivering unprecedented analysis on the efficacy and superiority of products. The unintended consequence, however, is the parallel rapid commoditization of categories that will be supervised by super intelligent machines who neither care about, promote nor recognize the emotional equity brands work to create.

AI advisors will come between you and your customers and future customers, focused entirely on clinical analysis of product bona fides, formulations, sourcing standards, and authentic delivery of promises. This means the strength of the brand relationship will be paramount to your future, alongside managing the narrative product story LLMs express about your business.

  • Your future can’t be left in the hands of AI opinion alone. Your brand’s relational strength and emotional equity through its Iconic status and reputation form the critical alchemy of your future business success.

If this article has you thinking and wondering aloud about the right path to follow, use the link below to air questions and start an informal conversation.

Looking for more food for thought? Subscribe to the Emerging Trends Report.

Bob Wheatley is the CEO of Chicago-based Emergent. Traditional brand marketing often sidesteps more human qualities that can help consumers form an emotional bond. Yet brands yearn for authentic engagement, trust and a lasting relationship with their customers. For more information, contact Bob@Emergent-Comm.com and follow on Twitter @BobWheatley.

Markets are drawn over time to commoditize. Courage can lead a brand to restore vitality and growth

How Courage Will Revitalize Business Growth

October 14th, 2024 Posted by Brand Beliefs, Brand differentiation, brand marketing, Brand preference, brand strategy, Commoditization, Differentiation, Disruption, Emotional relevance, Marketing Strategy 0 comments on “How Courage Will Revitalize Business Growth”

Fighting the creep of commoditization…

As all business categories grow and evolve, there’s a law of physics in the food, beverage and retail industries that comes into play to establish an implicit set of brand rules and behaviors. This often emerges in the form of industry accepted standards, regulatory requirements, consumer and trade partner expectations and competitive actions.

A pervasive condition, it creates a palpable magnetic momentum that pushes category participants towards the middle of the market — and away from whatever unique corner of the industry they originally occupied. Over time, it will manifest in comparable features, benefits, even pricing and product offerings. The edges of distinction get dull.

At its zenith it translates into sameness across business practices, supply chain standards and manufacturing processes – all helped along by growing similarity in product development as well as the technical processes employed for manufacturing.

The impact of category commoditization unleashed

As category players inevitably work to drive scale, secure efficiency gains, improved margins and retail leverage, brands level out their distinctiveness to appeal to a wider mass market. This happened in the dairy aisle cheese category as the major branded players eventually started to compete on price rather than disruptive innovation. The similarity in product choices and packaging helped commodify the consumer’s perception of quality.

The outcome? “Cheese is cheese is cheese” took root and the share leadership torch passed to private label products. Inevitable because the product experience wasn’t substantially different between private and national brands.  This ushered in an era of tit for tat price wars as combatants worked to build share by reducing price at the expense of brand equity and margins.

We encountered this condition and moved to tackle it while representing Sargento. The agency/client team launched a multi-stage process aimed at repositioning the brand, optimizing the product portfolio and walking away from “all things to all people” forms of marketplace behavior. The resulting “premiumization” of the Sargento brand showed up in new European influenced package design, new value-added products called Artisan Blends that borrowed equity from artisanal cheese makers. Most important to success, breaking out required recasting who the core customer is. We narrowed and focused on a high involvement premium cheese consumer called The Food Adventurer – roughly 26% of the category shoppers.

The customer priority decision was key to breaking the back of commoditization. It pushed our marketing team to rethink everything from innovation to messaging, media and market strategies while building in separation from all other players in the dairy case. The impact was startling. Sargento brand strength and resilience multiplied, while also helping establish more control over what was a price-driven business. The impact resulted in share gains against a larger competitor and fostered a spirit of creativity that set the stage for break-through new category ideas like the Balanced Breaks snack cheese innovation.

We’ve observed commoditization conditions blossoming in other places such as cell phones, computers, airlines and mainstream cars. When meaningful brand differentiation and separation dissipates, market leverage moves almost automatically to favor expanded budget investments that chase “top of mind awareness.” When the brand isn’t remarkably, authentically different, dependency on profit sapping awareness spending is required to keep repeatedly reminding consumers of the product features. Whereas distinctive and differentiated brands are naturally alluring and therefore less dependent on heavy media spend to attract and retain a loyal following.

When meaningful differentiation starts to fade, courage is required

It takes vision, fortitude and courageous leadership to create and launch the antidote to commoditization. You must be willing to tear up the category conventions rule book and seek fresh territory in the form of:

  • New and emerging markets where competition is still forming.
  • Bravery to jump over category behavior traditions and pursue whitespace opportunities that offer a new solution.
  • Become a disruptor – a challenger brand that pursues radical differentiation designed to shut the door on equity robbing price competition.

When a brand is informed by a clear set of values, a strong “why” and a purpose that brings deeper meaning beyond transactions, it’s easier to recognize the advance of commodity behaviors and react proactively.

Sound strategy ignites the engine

Pushing the envelope of new category creation is a dynamic and powerful exercise intended to dial the brand far enough to the right or left of the vanilla middle that a new, ownable category can be established.

  • Distinctiveness here is the essence of sound strategy because the goal is to offer a product or service the consumer can’t get anyplace else.

Here’s the catch: the forces at work in every category that drive brands towards similarity are fierce. Thus, vigilance around observing the creep of commodity inducing behaviors in pursuit of a mass market are ever present. Simply said, you will face it eventually. Your courageous efforts to catch this early before it takes root will pay long term dividends.

The last thing you want to hear is the word “mature” to describe your brand, which is code for the plateau you reach just before tipping towards the slippery slope of declining relevance.

If this discussion has you thinking about remedies to ever-present commodity pressures in your category — and fresh thinking around renewed emphasis on differentiation — use the email link below to start an informal conversation about refreshing your plans and programs.

Looking for more food for thought? Subscribe to the Emerging Trends Report.

Bob Wheatley is the CEO of Chicago-based Emergent. Traditional brand marketing often sidesteps more human qualities that can help consumers form an emotional bond. Yet brands yearn for authentic engagement, trust and a lasting relationship with their customers. For more information, contact Bob@Emergent-Comm.com and follow on Twitter @BobWheatley.

Archives

Categories